Thorough Examination of Various Loan Options in the UK
How Do Personal Loans Differ from Secured Loans?
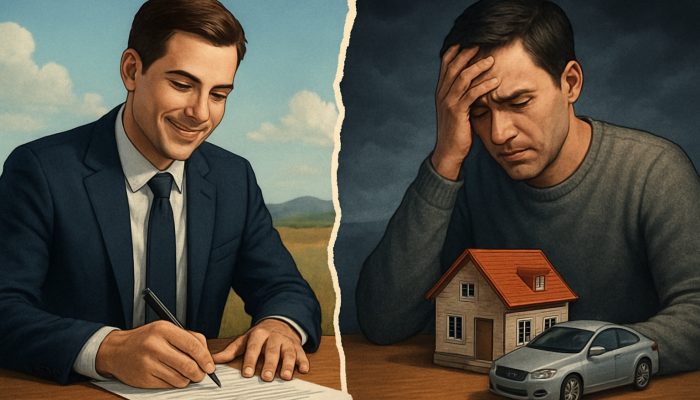
Personal loans and secured loans are designed to meet different financial needs, each with distinct characteristics. Personal loans are primarily unsecured, indicating that they do not require collateral. This feature makes them attractive to borrowers who may not possess significant assets to pledge. In contrast, secured loans necessitate the borrower to offer an asset, such as a property or vehicle, as security. While this can result in lower interest rates, it also entails the risk of losing the asset if repayments are not made on time.
Before deciding to pursue personal loans, it is crucial for borrowers to assess their financial condition, including income stability and credit history. Lenders will thoroughly evaluate these factors to determine eligibility and interest rates. Secured loans might be preferable for those requiring larger amounts or extended repayment durations, but they necessitate the borrower to maintain the pledged asset.
Ultimately, the decision between personal and secured loans depends on individual financial circumstances, risk tolerance, and the intended purpose of the funds. Understanding which option aligns best with one’s financial objectives is vital for making a well-informed choice.
What Unique Mortgage Products Can You Find in the UK?
The UK offers a range of specialist mortgage products tailored to various borrower needs, including options like fixed and variable rate mortgages. Fixed-rate mortgages provide stability with set monthly payments over a defined term, simplifying budgeting for homeowners. On the other hand, variable rate mortgages may fluctuate in response to market conditions, potentially offering lower initial payments while exposing borrowers to the risk of increased costs down the line.
It is essential for prospective homeowners to grasp the differences between these mortgage types. Fixed-rate mortgages suit those who prioritise financial predictability, while variable rates may appeal to borrowers willing to accept some risk in exchange for the potential of lower payments.
Borrowers should also consider other specialised mortgage options, such as interest-only mortgages or buy-to-let mortgages. Each product comes with specific requirements and features, making thorough research and consultation with a mortgage advisor crucial for selecting the most suitable option for property acquisition.
How to Utilise Overdraft Facilities and Credit Cards Wisely
In the UK, overdraft facilities and credit cards are widely used short-term credit solutions, designed to assist with cash flow management. An overdraft allows account holders to withdraw funds beyond their available balance, up to a predetermined limit. This can serve as a financial safety net for unexpected expenses, but it is important to be aware that fees and interest rates can vary significantly between banks.
Credit cards offer another flexible borrowing option, enabling users to make purchases and repay over time. Many credit cards come with interest-free periods, which can be beneficial for managing short-term financial needs. Understanding the terms of these cards is vital, as high-interest rates may apply if balances are not settled promptly.
Both borrowing methods require careful consideration of repayment terms and potential costs. A thorough understanding of their differences will empower consumers to make informed decisions about which facility best suits their financial situation and spending habits.
What Important Information Should You Know About Payday Loans and Alternative Short-Term Financing?
Payday loans are a contentious form of short-term financing in the UK, providing rapid access to cash for urgent expenses. they often carry exceptionally high interest rates and fees, making them a precarious choice for many borrowers. It is crucial to fully understand the associated costs and risks before considering this type of loan.
Alternatives to payday loans include credit unions and peer-to-peer lending platforms, which may offer more favourable terms. These alternatives often promote responsible lending practices and may offer better support for borrowers facing financial challenges.
When evaluating short-term financing options, consumers should weigh the potential costs against the urgency of their needs. It is vital to consider how each choice will impact long-term financial health while exploring all available avenues for assistance.
What Funding Options Are Accessible for Students?
In the UK, student loans are a crucial means of financing higher education. Government-backed student loans typically provide lower interest rates and flexible repayment options based on income levels. Graduates begin repayments only after their earnings surpass a specified threshold, easing financial management post-graduation.
Private student loans represent another option but usually present higher interest rates and less flexible repayment terms. It is essential for students to compare these options carefully and consider their long-term financial ramifications, especially concerning future career prospects.
Understanding the differences between government and private student loans can significantly impact a graduate’s financial future. Careful planning and research can empower students to make informed choices that align with their educational and career aspirations.
Evaluating Your Financial Capability Prior to Securing a New Loan
How to Perform Detailed Income and Expenditure Assessments
In the UK, lenders conduct thorough income and expenditure assessments to ascertain a borrower’s capability to manage a new loan. This evaluation involves comparing monthly income with regular outgoings, such as rent, utilities, and other financial obligations. The goal is to ensure that borrowers can sustainably meet repayment commitments without compromising their financial wellbeing.
Having a solid grasp of your financial situation is essential before approaching a lender. By developing a detailed budget that outlines income and expenses, you can ascertain how much you can afford to borrow. This proactive approach not only boosts your chances of loan approval but also helps to prevent financial overreach.
The Financial Conduct Authority (FCA) establishes guidelines that lenders must adhere to when assessing affordability. Familiarity with these regulations empowers you to ask informed questions and negotiate more advantageous terms, ensuring you secure a loan that aligns with your financial capabilities.
What Is the Method for Assessing Your Credit Score?
Your credit score plays a pivotal role in determining your eligibility for a loan in the UK. Lenders use credit scores to evaluate the likelihood of repayment based on your financial history. A strong credit score can unlock more competitive interest rates and borrowing terms, while a poor score may limit your options.
To assess your credit score, lenders typically examine your credit history, including past loans, credit card usage, and any missed payments. This review helps them understand your borrowing behaviour and risk profile. Regularly checking your credit report is advisable to ensure its accuracy and rectify any discrepancies that could adversely affect your score.
Enhancing your credit score prior to applying for a loan can significantly improve your borrowing potential. Simple actions, such as making timely bill payments, reducing outstanding debts, and limiting new credit applications, can contribute to a healthier financial profile, making you a more attractive candidate to lenders.
In What Ways Do Existing Debts Impact Your Loan Application?
Existing debts can considerably affect your ability to obtain a new loan in the UK. Lenders evaluate your total debt-to-income ratio to ascertain how much additional borrowing you can realistically manage. A high level of existing debt may raise concerns for lenders, suggesting that you could struggle to meet new repayment responsibilities.
Before applying for a new loan, it is crucial to calculate your current debt obligations and how they fit into your overall financial framework. This includes analysing all monthly payments, such as mortgages, credit cards, and personal loans. A clear understanding of your debt status can inform your borrowing decisions and help you avoid financial strain.
If you discover that existing debts may impede your loan application, consider strategies to reduce your debt burden. This could involve consolidating loans, negotiating lower interest rates, or devising a repayment plan prioritising high-interest debts. Taking these measures can enhance your financial standing and improve your chances of loan approval.
Professional Guidance on Key Questions to Pose to a Lender Regarding a New Loan
What Typical Early Repayment Charges Should You Expect?
Early repayment charges (ERCs) are fees that lenders may impose if a borrower repays their loan ahead of the agreed schedule. In the UK, these charges can vary significantly based on the lender and the specific loan type. It is essential for borrowers to understand these fees, especially if they may wish to pay off their loans early.
Typically, ERCs are calculated as a percentage of the remaining loan balance or as a fixed fee. Borrowers should inquire about these charges during the application process to avoid unexpected costs later on. Some lenders provide products without ERCs, offering greater flexibility for borrowers anticipating changes in their financial situations.
When discussing ERCs with lenders, it is prudent to ask about the conditions under which these charges apply. Knowing the specific terms can assist borrowers in making informed decisions regarding their loan options and planning any future repayment strategies that might involve early settlement.
What Key Differences Should You Understand When Comparing Fixed and Variable Rates?
Gaining clarity on the differences between fixed and variable interest rates is essential when selecting a loan. Fixed-rate loans offer certainty, as the interest rate remains constant for the entire loan term. This predictability is beneficial for budgeting, particularly in uncertain economic times when interest rates may increase.
Conversely, variable rate loans can fluctuate based on market conditions, potentially presenting lower initial rates but also the risk of increasing payments over time. Borrowers should thoughtfully consider their financial circumstances and risk tolerance when choosing between these two options. For instance, individuals with stable incomes might prefer the predictability of fixed rates, while others may be comfortable with potential variability.
Real-world scenarios can illustrate the consequences of these choices. For example, if interest rates rise substantially, borrowers with variable loans may encounter higher monthly payments, while those with fixed-rate loans would remain unaffected. Evaluating these situations can empower individuals to make informed decisions that align with their financial goals.
What Considerations Should Influence Your Decision on Loan Term Length?
Choosing the right loan term length is a critical decision that can affect both monthly payments and total interest costs. In the UK, loan terms vary widely, typically from a few months to several years. Shorter terms often yield higher monthly payments but lower total interest, while longer terms may ease monthly financial pressure at the cost of increased overall interest paid.
When evaluating loan terms, borrowers should consider their financial circumstances and future plans. A shorter term may suit those with stable incomes capable of managing higher payments, while longer terms might benefit individuals seeking lower monthly costs due to fluctuating income or other financial commitments.
To make an informed choice, borrowers can create a repayment schedule that outlines various term lengths and their corresponding costs. This exercise can clarify the trade-offs involved and help individuals select a loan term that balances their monthly budget against their long-term financial objectives.
In What Ways Do Credit Scores Impact Your Loan Offers?
Credit scores play a significant role in determining the loan offers you receive from lenders in the UK. A higher credit score typically translates to better interest rates and more favourable terms, while a lower score can restrict your options and lead to higher borrowing costs. Understanding how credit assessments work is crucial for prospective borrowers.
When lenders evaluate your credit score, they consider various factors, including your payment history, credit utilisation, and the length of your credit history. These elements help lenders assess your reliability as a borrower. Regularly reviewing your credit report is advisable to address any issues that may negatively impact your score prior to applying for a new loan.
To enhance your credit score, consider practical measures such as timely payments, reducing outstanding debts, and refraining from new credit applications before seeking a loan. By taking these proactive steps, you can bolster your creditworthiness and increase your chances of receiving appealing loan offers.
What Inquiries Should You Make About Overpayment Flexibility?
When negotiating a new loan, it is vital to ask about overpayment flexibility. Many lenders in the UK allow borrowers to make additional payments without incurring penalties, which can significantly lower the total interest paid and shorten the loan term. Understanding these options can lead to substantial long-term savings.
During discussions with lenders, inquire about the specific terms regarding overpayments. Some may limit the annual amount you can overpay or may charge fees for exceeding those limits. Clarifying these details can assist you in planning your repayment strategy effectively and taking advantage of opportunities to pay down your loan more quickly.
Incorporating overpayments into your financial strategy can facilitate faster debt repayment and enhance your financial wellbeing. By proactively managing your loan and exploring overpayment options, you can alleviate your financial burden and achieve your goals more efficiently.
Research-Backed Insights on Critical Questions for Lenders Regarding New Loans
How to Grasp Fee Structures and Hidden Costs
Understanding the fee structures associated with loans is essential for avoiding unexpected surprises during the approval process. Lenders in the UK may impose various fees, including arrangement fees, valuation fees, and early repayment charges. Being aware of these costs can help you budget accurately and mitigate unforeseen financial strain.
During discussions with lenders, request a detailed breakdown of all potential fees linked to the loan. This transparency allows for more effective comparison among different lenders and aids in making informed decisions. Some lenders may offer loans with no arrangement fees, significantly reducing the overall cost of borrowing.
Thoroughly reviewing the terms and conditions is vital to identify any hidden charges that might not be immediately evident. By comprehending the entire fee structure, you can ensure that you select a loan that aligns with your financial goals while avoiding unnecessary expenses.
What Insurance Requirements Should You Discuss with Lenders?
When applying for a loan, lenders may require borrowers to secure insurance to guard against unforeseen circumstances. This is particularly common with secured loans, where the lender seeks to ensure that the asset remains protected. Understanding the insurance requirements can assist borrowers in managing their finances more effectively.
Payment protection insurance (PPI) is one type of coverage that some lenders might recommend. It can cover loan repayments in the event of illness, unemployment, or other unexpected situations. Assessing whether this insurance is necessary for your circumstances and comparing different policies to find the best fit is crucial.
Discussing insurance requirements with lenders may also unveil potential savings. Some lenders provide bundled loan and insurance packages at discounted rates. By exploring these options, borrowers can not only meet lender requirements but also secure their financial future against unexpected challenges.
How to Understand the Loan Application Timeline
Comprehending the loan application timeline is vital for establishing realistic expectations. In the UK, the process typically unfolds in several stages, from initial inquiry to the disbursement of funds. Knowing what to expect at each stage can aid borrowers in navigating the process more smoothly.
Initially, borrowers submit their application, which includes personal and financial information. Lenders will then conduct affordability assessments and credit checks, which can take anywhere from a few days to several weeks, depending on the lender and the complexity of the application.
Once approved, borrowers receive an offer detailing the loan terms. After acceptance, funds are usually released within a few days. Being aware of this timeline enables borrowers to plan accordingly, ensuring that they have access to the necessary funds when required and can manage their finances effectively throughout the process.
Key Documentation Required for Loan Applications
What Proof of Identity and Residential Address Is Required?
When applying for a loan in the UK, lenders require proof of identity and residential address to comply with legal regulations. Acceptable documents typically include passports, driving licences, and utility bills. These documents serve to verify your identity and ensure compliance with anti-money laundering laws.
Preparing these documents in advance can streamline the application process. Ensuring that all paperwork is current and accurate is essential to avoid complications during verification and enhance your chances of a smooth approval.
Some lenders may also accept digital documentation, facilitating a more convenient application process. Familiarising yourself with the specific requirements of your chosen lender can ensure that you provide the correct documentation and meet all necessary criteria.
What Evidence of Employment and Income Is Necessary?
Lenders in the UK require proof of employment and income to evaluate a borrower’s capability to repay a loan. Commonly accepted documents include payslips, tax returns, and bank statements. These documents provide insight into your financial stability and assist lenders in assessing your affordability.
When collecting proof of employment and income, ensure that the documents are recent and accurately reflect your current financial situation. Consistency across all documentation is crucial, as any discrepancies can raise concerns for lenders and potentially delay the application process.
For self-employed individuals, additional documentation may be necessary, such as business accounts or tax returns from the past few years. Supplying comprehensive and precise information can enhance your credibility as a borrower and boost your chances of securing a loan.
How Do Lenders Analyse Bank Statements?
Lenders frequently examine bank statements as part of the loan application process to evaluate a borrower’s financial habits. This analysis helps lenders understand spending patterns, income consistency, and overall financial health. Key transaction patterns that lenders scrutinise include:
- Monthly income deposits
- Regular outgoing payments
- Overdraft usage
- Large or irregular transactions
- Saving patterns
- Payment of existing debts
- Any missed payments or defaults
Reviewing your bank statements before applying for a loan can yield valuable insights into your financial situation. Identifying negative patterns can empower you to proactively address potential concerns, thereby enhancing your chances of a successful application.
Maintaining a healthy bank balance and demonstrating responsible financial behaviour can improve your attractiveness to lenders, leading to better loan offers and terms.
Effective Strategies for Inquiring About a New Loan
Negotiation Techniques for Better Loan Terms
Negotiating loan terms can result in significant savings in the UK lending landscape. Borrowers should approach lenders with a clear understanding of their financial situation and the terms they desire. Being well-prepared enhances the effectiveness of discussions, potentially resulting in reduced rates or waived fees.
When negotiating, it is essential to highlight your strengths as a borrower, such as a strong credit score or steady income. Presenting evidence of your financial reliability can strengthen your case and encourage lenders to offer more favourable terms. Exploring offers from multiple lenders can further bolster your negotiating position.
Being open to discussing various loan features, such as repayment flexibility or overpayment options, can also lead to better terms. By demonstrating a willingness to collaborate, borrowers can often secure a loan agreement that aligns more closely with their financial goals and requirements.
What Regulatory Protections Are Available to Borrowers?
Understanding the regulatory protections in place in the UK can safeguard borrowers throughout the loan process. The Financial Conduct Authority (FCA) oversees lending practices, ensuring that lenders adhere to fair and transparent guidelines. Familiarity with these regulations empowers borrowers to ask pertinent questions and advocate for their interests.
For instance, the FCA mandates that lenders conduct thorough affordability assessments before approving loans. This requirement protects borrowers from incurring unmanageable debt and promotes responsible lending practices. Being aware of these regulations can enhance borrowers’ confidence during their interactions with lenders.
Borrowers should inquire about their rights, including the right to file a complaint if they feel they have been treated unfairly. Understanding these protections can provide peace of mind and ensure that borrowers receive fair treatment throughout the lending process.
What Steps Should You Take If Your Financial Situation Changes?
Life can be unpredictable, and circumstances may change after securing a loan. It is crucial to understand the options available if you encounter financial challenges, such as job loss or unexpected expenses. Many lenders in the UK offer forbearance options, allowing borrowers to temporarily reduce or suspend payments without incurring severe penalties.
When discussing loan terms with lenders, inquire about their policies regarding changes in circumstances. Understanding the flexibility offered can alleviate concerns, knowing that you have options if your financial situation fluctuates unexpectedly. Some lenders may allow adjustments to repayment schedules or provide hardship programmes to support borrowers in distress.
Proactively discussing these scenarios with lenders can help you prepare for the future and ensure that you are equipped to handle any challenges that may arise during the loan term. This foresight contributes to a more secure financial experience.
What Should You Ask About All Costs Involved?
When considering a new loan, it is vital to question lenders about all associated costs. Beyond the interest rate, borrowers should inquire about arrangement fees, early repayment penalties, and valuation costs. Understanding the total expenses involved in obtaining a loan can inform your decision-making and prevent unexpected financial burdens.
During discussions with lenders, request a comprehensive breakdown of all fees and charges. This transparency enables you to compare offers from various lenders more effectively and identify the most cost-effective option. Some lenders may provide no or low fees as a competitive strategy, which can significantly impact the overall cost of borrowing.
Being thorough in your inquiries can also clarify any terms that may seem ambiguous. Understanding the complete range of costs associated with a loan can empower borrowers to negotiate better terms and ensure they select a loan that aligns with their financial objectives.
How to Evaluate Interest Rate Options?
When considering a loan, clarifying interest rate options is critical for informed decision-making. Borrowers should inquire whether rates are fixed or variable, as this can significantly affect monthly payments and overall borrowing costs. Fixed rates offer stability, while variable rates may change based on market conditions.
It is important to understand any caps or floors associated with variable rates. Knowing the potential limits on interest rate changes can help borrowers gauge their risk tolerance and make informed choices about which loan structure aligns with their financial situation.
Engaging lenders in discussions about interest rate options may also reveal potential promotional rates or discounts for specific borrowers. By being proactive in these conversations, you can secure a loan that not only meets your immediate needs but also aligns with your expectations regarding future economic conditions.
How Interest Rates Impact Your Loan Repayments
What Effect Does the Base Rate Have?
The Bank of England’s base rate is a fundamental factor in determining interest rates for loans in the UK. When the base rate fluctuates, it can directly affect the rates offered by lenders, especially for variable rate loans. Understanding these dynamics can help borrowers anticipate potential changes in their loan repayments.
For instance, if the Bank of England raises the base rate, borrowers with variable rate loans may experience increased monthly payments. Conversely, a decrease in the base rate can result in lower repayments. Staying informed about these changes can provide valuable insights for borrowers considering new loans or those looking to refinance existing debt.
Awareness of base rate influences can also guide strategic decisions regarding loan timing. If you anticipate a rise in interest rates, securing a loan sooner could be beneficial to lock in lower rates before they increase further.
How Are APR Calculations Made?
The Annual Percentage Rate (APR) is a crucial figure that reflects the true cost of borrowing. It encompasses not only the interest rate but also any additional fees associated with the loan. Understanding how APR is calculated can empower borrowers to effectively compare different loan offers.
When assessing APR, borrowers should factor in all associated costs, including arrangement fees and insurance requirements. A loan with a lower interest rate but higher fees may end up being more expensive than one with a slightly higher interest rate but lower fees. By evaluating the APR, borrowers can make more informed decisions about which loan is the most economically viable.
It is also important to remember that APR can vary depending on the borrower’s creditworthiness. Higher credit scores generally lead to lower APRs, making it essential for borrowers to understand how their financial profile influences the rates offered to them.
What Advantages Does Fixed-Rate Security Provide?
Fixed-rate loans offer substantial benefits for borrowers seeking certainty in their repayments. By securing an interest rate for the entire duration of the loan, borrowers can effectively manage their budgets without worrying about fluctuations in market rates. This stability is particularly valued by many households in the UK, especially during periods of economic uncertainty.
Choosing a fixed-rate loan can also shield borrowers from potential interest rate hikes. In a climate of rising rates, those with fixed rates enjoy lower payments compared to borrowers with variable rates who may see their costs escalate. This predictability allows for better financial planning and peace of mind.
It is crucial to weigh the trade-offs. Fixed-rate loans may feature higher initial rates compared to variable options. Assessing personal financial situations and future plans can help borrowers determine whether the security of a fixed rate aligns with their long-term objectives.
Final Thoughts on Securing Your Loan Agreement
What Key Elements Should You Scrutinise in Your Contract?
Before signing a loan agreement in the UK, a thorough review of the contract is imperative to avoid misunderstandings. Borrowers should carefully read all terms and conditions, focusing on interest rates, repayment schedules, and any fees related to the loan. This diligence can help prevent future disputes and financial surprises.
It is advisable to seek clarification on any clauses that appear ambiguous or concerning. Engaging directly with the lender to address these points ensures that you fully comprehend your obligations and rights under the agreement. This proactive approach can protect your interests and contribute to a smoother borrowing experience.
Consider having a trusted advisor or legal professional review the contract. Their expertise can provide valuable insights and help identify any potential pitfalls that may not be immediately apparent, ensuring that you enter into the agreement with confidence.
What Post-Approval Support Services Can You Access?
After securing a loan, utilising post-approval support services can enhance your borrowing experience. Numerous lenders in the UK offer ongoing advice and resources to assist borrowers in managing their loans effectively. This support can be invaluable, particularly during challenging financial circumstances.
Inquire about the availability of customer service and support options once your loan is approved. Some lenders provide dedicated account managers or online resources to assist with repayment strategies, budgeting advice, and financial planning. Taking advantage of these services can help you stay on track and maximise the benefits of your loan.
Maintaining open communication with your lender fosters a positive relationship. If financial challenges arise, reaching out for assistance can lead to solutions that help you navigate difficulties while keeping your loan in good standing.
How to Effectively Plan Your Repayment Schedule?
Establishing a repayment schedule is a vital step in managing your loan effectively. A clear schedule enables borrowers to track their progress against the original loan terms and ensures timely payments. Key milestones to incorporate into your schedule include:
- Loan approval date
- First payment due date
- Monthly payment amounts
- Interest rate changes (if applicable)
- Options for early repayment
- Final repayment date
- Any planned overpayments
By outlining these milestones, borrowers can maintain accountability and remain organised throughout the loan term. Regularly reviewing the repayment schedule can also help identify opportunities for additional payments or adjustments based on changing financial circumstances.
Adopting a structured repayment approach can contribute to improved financial health and a more successful borrowing experience, ultimately leading to the timely fulfilment of loan obligations.
What Signature Authentication Procedures Must Be Followed?
Proper signature authentication during the loan agreement process is essential for verifying the identity of all parties involved. In the UK, lenders typically require that signatures on loan documents are authenticated to uphold the legal validity of the contract. This process helps prevent fraud and ensures that all parties are in agreement.
Borrowers should be prepared to present identification documents that correspond with the names on the loan agreement. Lenders may also have specific procedures for witnessing signatures, which can vary by institution. Understanding these requirements can facilitate a smoother signing process and help prevent potential delays.
In certain cases, lenders might also require notarisation of the loan documents, particularly for substantial loans. Engaging a qualified notary public can provide an added layer of security and authenticity, ensuring that the agreement meets all legal standards and is enforceable in the event of any disputes.
What Role Does a Notary Public Play in Loan Agreements?
Involving a qualified notary public during the loan agreement process can enhance the security and authenticity of the contract. In the UK, notaries are authorised to witness signatures and verify the identity of parties involved in legal documents. Their participation can provide reassurance for both borrowers and lenders.
Notarisation is especially important for significant loan agreements, as it adds an extra layer of protection against fraud. By ensuring that all signatures are verified, notaries help maintain the integrity of the loan process and confirm that all parties have willingly entered into the agreement.
When considering a loan, it is prudent to inquire with lenders about their notarisation requirements. Understanding these protocols can streamline the signing process and ensure that all legalities are properly addressed, contributing to a smoother borrowing experience.
Frequently Asked Questions
What Types of Loans Can Be Secured in the UK?
In the UK, common loan types include personal loans, secured loans, mortgages, credit cards, and payday loans. Each type serves different financial needs and comes with unique terms and conditions.
How Can I Enhance My Credit Score Before Applying for a Loan?
To improve your credit score, make timely payments, reduce outstanding debts, limit new credit applications, and review your credit report for inaccuracies. These actions can boost your creditworthiness and enhance your chances of loan approval.
What Are Early Repayment Charges?
Early repayment charges (ERCs) are fees imposed by lenders when a borrower pays off their loan before the agreed term. These charges can vary, making it essential to understand them before finalising a loan agreement.
How Do Fixed and Variable Interest Rates Compare?
Fixed interest rates remain unchanged throughout the loan term, providing stability. In contrast, variable rates can fluctuate based on market conditions, potentially leading to lower initial payments but increased costs over time.
What Documentation Is Necessary for a Loan Application?
Common documentation includes proof of identity (passport or driving licence), proof of address (utility bills), and evidence of income (payslips or tax returns). Lenders require these to assess your eligibility.
Can I Negotiate Loan Terms with Lenders?
Yes, negotiating loan terms is feasible. Prepare by understanding your financial situation and comparing offers from different lenders. Highlight your strengths as a borrower to secure better rates or terms.
What Should I Do If I Am Unable to Make My Loan Payments?
If you are unable to make loan payments, contact your lender immediately. Many offer forbearance options or payment plans to assist borrowers facing financial difficulties. Maintaining open communication is crucial.
How Long Does the Loan Application Process Generally Take?
The loan application process in the UK can vary from a few days to several weeks, depending on the lender and the complexity of the application. Factors include credit checks and documentation review.
Are There Hidden Costs Associated with Loans?
Yes, loans may come with hidden costs such as arrangement fees, valuation fees, or insurance requirements. Always request a detailed breakdown of all associated costs from lenders before agreeing to a loan.
What Is the Importance of the Bank of England’s Base Rate?
The Bank of England’s base rate influences interest rates for loans in the UK. Changes in the base rate can affect borrowing costs, particularly for variable rate loans, impacting monthly repayments.
Visit our Facebook profile today!
This Article Was First Found On: https://www.debtconsolidationloans.co.uk
The Article Questions to Ask a Lender About a New Loan in the UK found first on https://electroquench.com