Comprehensive Guide to Understanding APR Calculations in the UK
In-Depth Analysis of Loan Terms for Informed Decisions
When evaluating loan offers from UK lenders, it is vital to conduct a thorough examination of the loan terms. This entails a detailed analysis of interest rates, fees, and any promotional offers that may apply. By understanding these components, you can ascertain the true cost of borrowing over the loan’s duration, empowering you to make informed financial decisions.
It’s important to remember that some lenders may advertise attractive introductory rates that could change after a specified period. Always consider the potential costs throughout the entire loan term rather than focusing solely on the initial rate. This holistic approach will help clarify your overall financial commitment.
How to Ensure Compliance with Regulatory Standards in Lending
Ensuring compliance with regulatory standards is crucial when assessing loan offers. It is essential to verify that the lenders you are considering adhere to the guidelines set forth by the <a href="https://www.debtconsolidationloans.co.uk/preparing-statements-if-your-spending-looks-risky/">Financial Conduct Authority (FCA)</a>. This regulatory body is dedicated to protecting consumers by promoting transparency and fairness in financial products across the UK.
While reviewing different offers, it is essential to ensure that lenders provide clear and accessible information regarding costs and associated risks. Such diligence not only safeguards your interests but also ensures access to reliable and trustworthy financial products.
How Can You Effectively Compare Representative APR Examples?
When comparing APR across varied loan offers, analysing representative examples can provide valuable insights into the practical implications of different loans. Here are some key advantages to consider for each loan type:
- Fixed-rate loans offer predictable monthly payments.
- Variable-rate loans may start with lower rates but can change over time.
- Secured loans typically present lower rates due to collateral backing.
- Unsecured loans provide greater flexibility but may come with higher rates.
Each of these factors can significantly influence your overall repayments. By investigating these examples, you can determine which loan type aligns best with your financial circumstances and objectives.
What Essential Factors Influence Your APR Comparisons?
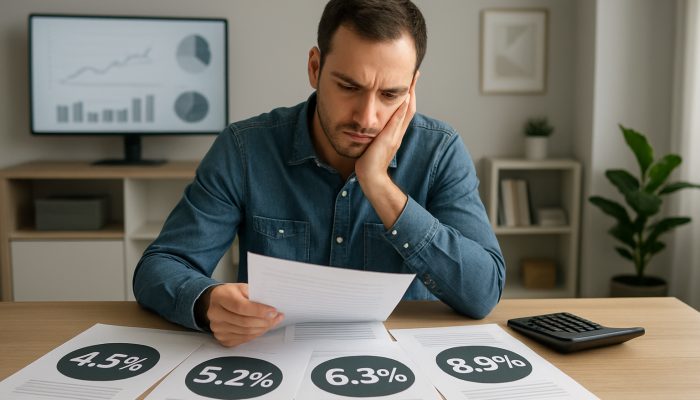
What Impact Does Your Credit Score Have on APR Offers?
Your credit score is a significant factor in determining the APR offered by various lenders. Generally, a higher credit score leads to lower interest rates, as lenders view you as a lower-risk borrower. Conversely, those with lower scores may encounter higher rates or limited borrowing options.
By understanding your credit score and its implications for loan offers, you can make more informed borrowing choices. Regularly reviewing your credit report helps identify areas for improvement, potentially leading to better rates in future borrowing situations.
Why Is Evaluating Additional Charges and Fees Important?
Evaluating additional charges is critical when comparing APR across different loan offers. These could include arrangement fees, early repayment charges, and other costs that greatly affect the overall expense of the loan. By considering these charges, you gain a clearer understanding of the actual costs associated with each credit agreement.
It is advisable to request a detailed breakdown of all potential fees from lenders. This level of transparency enables you to compare offers effectively and make an informed decision that meets your financial requirements.
How Do Repayment Periods Influence the Cost of Loans?
The repayment period of a loan significantly affects both the APR and your monthly payments. Typically, longer repayment periods may lead to lower monthly payments but can result in a higher total interest paid over the life of the loan. In contrast, shorter terms may entail higher monthly payments but reduced overall interest costs.
When assessing offers, consider how the repayment period aligns with your financial goals. Finding a balance between manageable monthly payments and the total loan cost is crucial for maintaining your financial health.
How Do Current Market Conditions Influence APR Rates?
Current market conditions have a profound impact on the APRs available from different lenders. Economic trends, changes in base interest rates, and competition among lenders all play a role in shaping the rates on offer. Staying informed about these developments can help you optimise your borrowing timing.
For example, during periods of economic uncertainty, lenders might increase rates due to perceived risks. Conversely, in a competitive market, lenders may lower rates to attract borrowers. Understanding these dynamics enhances your ability to secure the best possible deal.
What Are the Key Eligibility Criteria for Borrowers?
Familiarity with borrower eligibility criteria is essential when comparing APRs. Lenders often set specific requirements regarding income levels, employment stability, and credit history, all of which can influence the rates they offer. Understanding these criteria helps you identify which lenders are likely to provide the most favourable terms.
Before applying for loans, it is prudent to assess your financial situation and how it aligns with lender requirements. This preparation can save you time and allow you to focus on the most suitable offers for your profile.
Strategic Approaches to Comparing APR Across Loan Offers
How to Leverage Real-World UK Banking Examples
Analysing real-world examples from UK banking can yield valuable insights into identifying hidden costs in credit card and personal loan offers. For instance, a borrower may find an appealing credit card with a low APR, only to discover substantial fees for balance transfers or cash withdrawals that negate the advantages.
Another frequent scenario involves personal loans that advertise low rates but are accompanied by high arrangement fees. By scrutinising these examples, borrowers can learn to look beyond advertised rates and consider the total cost of borrowing, ensuring they make well-informed choices.
What Insights Can Expert Analysis Offer on Rate Differences?
Market conditions can create significant disparities in APRs between high street banks and online lenders. High street banks may provide stability and customer service but often charge higher rates due to their operational costs. In contrast, online lenders typically offer more competitive rates as they function with lower overheads.
Understanding these variations empowers borrowers to choose lenders that best meet their needs. An analysis of current market trends can help identify which lenders are likely to present the most advantageous rates based on your specific circumstances.
What Practical Steps Can You Take for Verification?
To ensure you are making well-informed decisions, consider implementing practical steps for verification. Contacting lenders directly can clarify any ambiguous terms or charges. Using official comparison tools approved for UK consumers can offer side-by-side evaluations of multiple offers.
These tools often highlight key differences in APR, fees, and terms, allowing you to make a more informed choice. Engaging with financial advisers can also provide tailored insights, ensuring you fully understand the implications of your loan choices.
Effective Techniques for Comparing APR Across Offers
Evaluating Fixed Rates Against Variable Rates
Evaluating fixed rates versus variable rates is a crucial aspect of comparing loan offers. Fixed rates provide predictability, enabling borrowers to budget with confidence. This is particularly beneficial during periods of rising interest rates, as your payments remain consistent.
On the other hand, variable rates may begin lower, appealing to those seeking immediate savings, but they pose the risk of fluctuating payments. Weighing the benefits and drawbacks of each option will assist you in determining the most appropriate borrowing strategy for your financial situation.
How to Optimise the Use of Online Calculators
Optimising the use of online calculators can simplify the process of evaluating loan rates. These tools allow you to input various loan amounts and terms, providing instant comparisons of potential repayments and total costs. This can help you avoid overlooking compounding effects that could significantly alter your financial obligations.
By effectively using these calculators, you can make informed decisions based on precise data. They can also illustrate how different APRs impact your overall repayment strategy, ensuring you choose the most advantageous offer.
Why Is Scrutinising Promotional Offers Essential?
Scrutinising promotional offers requires careful examination to avoid unexpected rate increases once the initial periods conclude. Many lenders promote attractive introductory rates that revert to higher standard rates after a defined duration. It is essential to understand the long-term consequences of these offers.
Before finalising any decisions, calculate the total cost of the loan over its entire term, including any potential rate increases. This diligence ensures you are not influenced by a temporary low rate that could lead to higher payments in the future.
How to Avoid Common APR Missteps?
What Strategies Aid in Identifying Deceptive Advertisements?
Identifying misleading advertisements is crucial to avoiding seemingly attractive offers that may conceal essential fees. Many lenders in the UK promote low APRs without disclosing additional costs, such as arrangement fees or insurance that can significantly inflate the overall price.
Always read the fine print and inquire about any applicable fees. This vigilance can shield you from falling for offers that ultimately cost more than anticipated, ensuring you make informed borrowing choices.
Why Is Independent Financial Advice Beneficial?
Seeking independent financial advice from authorised advisers can clarify the complexities of navigating loan terms. These professionals provide insights tailored to your financial situation, helping you understand the implications of various offers and ensuring you choose the most beneficial option.
Independent advisers possess extensive knowledge of the lending landscape and can assist you in evading common pitfalls. Their expertise can prove invaluable, particularly for first-time borrowers who may feel overwhelmed by the multitude of options available.
How to Stay Informed About Annual Changes in the Lending Market?
Staying informed about annual changes in the lending market is essential for maintaining accurate comparisons. Economic fluctuations, such as changes in the Bank of England’s base rate, can significantly affect the APRs offered by lenders. Keeping abreast of these changes allows you to determine the best time to refinance or explore new credit options.
Regularly reviewing your financial situation in conjunction with market conditions empowers you to make timely decisions. This proactive approach ensures you remain aware of the best available rates and products.
Why Is Comparing Multiple Lenders Important for Comprehensive Insights?
Comparing multiple lenders is crucial for uncovering the true cost of credit. Each lender may present their APRs differently, often omitting significant fees. By investigating offers from various institutions, you can ensure a thorough understanding of what each loan entails.
Take the time to gather and compare detailed information from several lenders. This diligence will aid you in selecting the most favourable terms, ultimately saving you money over the life of the loan.
How to Understand the Calculation Methods for APR?
Understanding the various calculation methods used to determine APR is essential for avoiding common pitfalls. Different lenders may employ distinct formulas, leading to variations in the APR quoted. Familiarising yourself with these methods allows for more accurate comparisons of offers.
For example, some lenders might include only specific fees in their APR calculations, while others may cover all potential costs. Recognising these differences ensures you can make well-informed comparisons and select the best financial product for your needs.
Steps to Finalise Your Loan Decision with Confidence
How to Confirm Total Repayment Amounts Accurately?
Confirming total repayment amounts is essential before signing any agreement with UK lenders. This step clarifies the complete cost of the loan, including interest and any associated fees. Understanding your total financial commitment is vital for avoiding surprises in the future.
Request a detailed breakdown of repayments throughout the loan term. This level of transparency enables you to assess whether the loan aligns with your budget and financial objectives, leading to a more informed decision.
What Key Aspects Should You Examine in Contract Conditions?
Examining contract conditions is a critical step in the loan finalisation process. This involves carefully reviewing your obligations, including payment schedules, penalties for late payments, and options for early repayment. Understanding these terms can help you avoid potential pitfalls down the line.
Pay particular attention to clauses concerning changes in interest rates or fees. Being aware of these conditions ensures you are fully informed about your commitments and can manage your finances effectively.
Why Is It Beneficial to Consult Independent Financial Advisers?
Consulting independent financial advisers before committing to a loan can provide invaluable insights. Financial advisers can assist you in evaluating all available options in accordance with current UK financial regulations and your specific personal circumstances. This support ensures you make the most informed decision possible.
Engaging with a professional can also clarify complex loan terms and conditions, empowering you to navigate the lending landscape with confidence. Their expertise can help you identify the best products suited to your financial needs and objectives.
Frequently Asked Questions
What Does APR Represent?
APR, or Annual Percentage Rate, denotes the total cost of borrowing expressed as a percentage. It encompasses interest rates and any additional fees, providing a comprehensive overview of what a loan will cost over a year.
How Can I Enhance My Credit Score Before Applying for a Loan?
You can improve your credit score by paying off outstanding debts, ensuring timely payments on bills, and reviewing your credit report for inaccuracies. Regular monitoring of your credit can also help maintain a healthy score.
Are There Various Types of APR?
Yes, there are different types of APR, including fixed APR, which remains constant throughout the loan term, and variable APR, which can change based on market conditions. Understanding these distinctions is essential for making informed borrowing decisions.
What Factors Should I Consider When Reviewing Loan Terms?
When reviewing loan terms, consider interest rates, repayment periods, fees, and any promotional offers. Understanding these elements will help you evaluate the true cost of borrowing and avoid unexpected charges.
How Can I Compare Loan Offers Effectively?
To effectively compare loan offers, gather detailed information from multiple lenders, including APR, fees, and repayment terms. Utilise online comparison tools to assess these offers side by side for a clearer understanding of your options.
What Is Meant by a Representative APR?
A representative APR is the interest rate that at least 51% of borrowers will receive for a specific loan product. It serves as a benchmark, but individual rates may vary based on creditworthiness and other factors.
Can I Negotiate Loan Terms with My Lender?
Yes, you can negotiate loan terms with your lender. Discussing your financial situation and credit history may lead to better rates or terms. It is worthwhile to inquire if the lender can accommodate your needs.
What Are the Consequences of Missing a Loan Payment?
Missing a loan payment can lead to late fees, increased interest rates, and potential damage to your credit score. It is crucial to communicate with your lender if you anticipate difficulties in making payments.
How Often Should I Review My Credit Report?
You should check your credit report at least once a year to ensure accuracy and monitor your credit health. Regular reviews can help you identify areas for improvement and prevent potential issues when applying for loans.
What Are the Key Differences Between Secured and Unsecured Loans?
Secured loans require collateral, such as property or a savings account, which can lower interest rates. Unsecured loans do not require collateral but typically carry higher interest rates due to the increased risk for lenders.
Visit our Facebook profile for more insights!
This Article Was First Found On: https://www.debtconsolidationloans.co.uk
The Article Compare APR Across Offers: Essential Steps for Borrowers found first on https://electroquench.com